

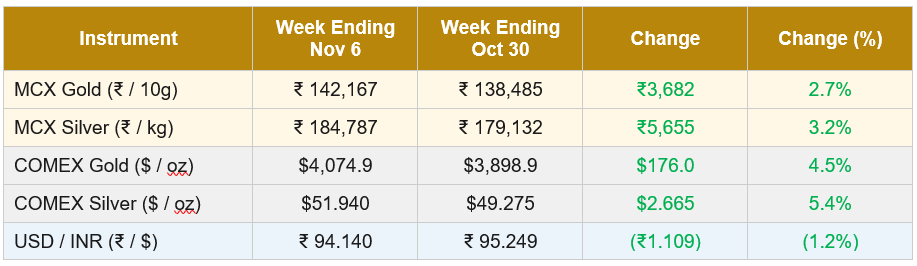
Macro Snapshot: Gold posted its best week since late August, but it got there on rate relief that had disappeared by Friday. COMEX gold rose 4.5% to $4,074.9 and silver 5.4% to $51.94 while cheaper oil pushed the odds of a December Fed hike down from about 71% on 30 October to 64% ahead of Friday’s payrolls, according to CME FedWatch readings reported by Benzinga and Reuters. The jobs data sent the odds back up to 74.8%, CNBC reported, a little higher than where the week began. Gold gave back only 0.9% on Friday, and holding the rest without that support is the test ahead.
Most of the relief came from politics and oil. Crude fell about 8% on Monday as Iran held talks with Qatari mediators, and it kept falling after Democrats won both chambers of Congress on 3 November, a slide Trading Economics linked to hopes of an earlier end to the Middle East conflict. WTI settled at $90.83 on Friday, down from $104.12 a week earlier, while Brent’s January contract ended at $98.32 against $113.43. The dollar index dropped 0.5% to 101.32 on 4 November, its weakest in more than a month, and gold jumped nearly 3.4% that day, its biggest one-day rise since 19 August.
Thursday went differently from 30 October, when a stock sell-off dragged gold down with it. The S&P 500 lost 4.4% in a rout led by AI data-centre stocks, its worst session since April 2025, but Treasuries rallied and December gold futures still settled 1% higher at $4,113.50. Friday’s jobs report then brought rates back into play. Payrolls rose 165,000 in October against a consensus of 59,000, unemployment slipped to 4.1%, and the dollar climbed 0.7% to its highest level since 29 October. Treasury yields still ended the week lower, the 10-year at 4.86% from 4.94% and the 30-year at 5.26% from 5.31%, which gave bullion some cushion.
Indian holders got a smaller share of the rally. Cheaper oil, along with ₹22,693 crore of foreign buying in Indian equities in November through 5 November (NSDL data cited by Upstox), pushed the rupee higher. The FBIL reference rate fell from 95.2492 on 30 October to 94.8755 on Monday and 94.1402 on Friday, a 1.2% gain for the rupee. PTI put the spot close at 93.98, from 94.76 a week earlier. Converted at the reference rates, COMEX gold’s rise comes to about 3.3% in rupee terms, and MCX gold managed 2.7%, roughly three-fifths of the dollar move.
Gold drivers: The World Gold Council’s Q3 Gold Demand Trends, published on 3 November, showed central banks buying 321 tonnes in the quarter, well above their five-year quarterly average of 227 tonnes. Indian demand fell 29% to 162.5 tonnes, and the Council lowered its 2026 forecast for India to 625 to 675 tonnes. Goldman Sachs cut its end-2026 target to $4,150 from $4,650 on 5 November, pointing to the Fed’s more hawkish stance. In the physical market, Reuters reported Indian dealers charging a premium of up to $4 an ounce over official prices, including the 15% import duty and 3% GST, down from $7 a week earlier even as more shoppers came into stores ahead of Diwali.
Silver drivers: Silver did better than gold overseas, and the COMEX gold-silver ratio eased to 78.5 from 79.1. Kotak Neo noted that weakness in copper and other industrial metals held the recovery back. At home, MCX silver’s 3.2% gain lagged the roughly 4.2% rise in COMEX silver once converted at the reference rates, which fits with more metal arriving after India relaxed silver import licensing in October. The Silver Institute still expects a 2026 deficit of 46.3 million ounces, though that has not stopped the price falling 27% since the start of the year.
Gold | MCX GOLD1!
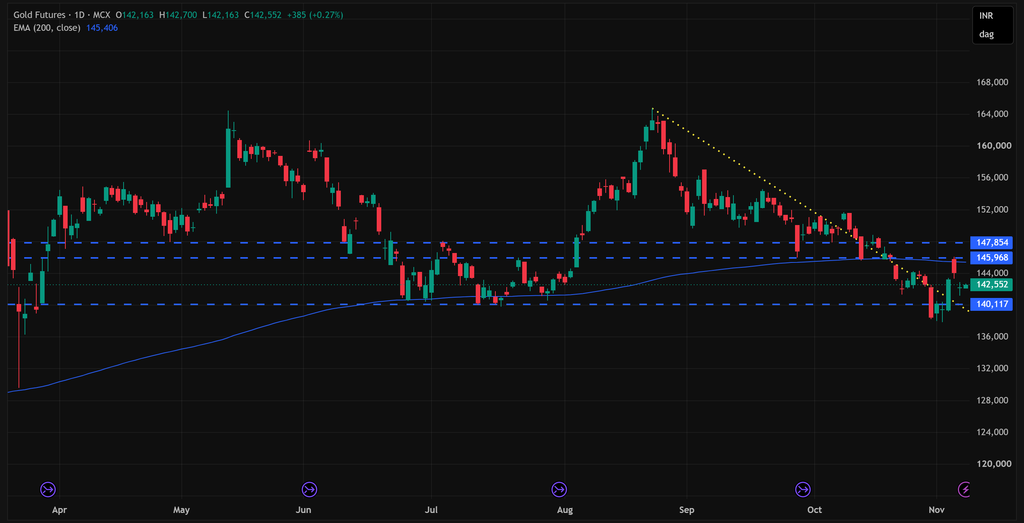
The December contract dipped just below its 30 October low on Tuesday, to around ₹138,000, before buyers stepped in. Wednesday’s rally lifted price back above the descending trendline from the August peak, and on Thursday the contract opened higher and reached about ₹146,000.
The move ran straight into the underside of the ₹145,968 to ₹147,854 band, the zone it broke through on 22 October, with the 200-day EMA just below at ₹145,406 (unadjusted). Sellers were waiting there. The contract closed Thursday at ₹144,095 and fell 1.3% on Friday to ₹142,167. On 28 October the bounce had stalled near ₹144,300 without reaching the band, so this was the second failed attempt, and the October breakdown stays in place until a daily close above ₹145,968.
Even so, the chart looks healthier than it did a week ago. The high near ₹146,000 is above the 28 October peak, which ends the run of lower highs that began in mid-October, and price is now trading above the trendline. What gold needs next is a higher low. If a pullback holds above roughly ₹138,000, the recovery has a base to build on; a close below it would put new lows back on the table. The ₹140,117 line on the chart comes from older, cheaper contracts and is not support for the December contract, which leaves a range of roughly ₹138,000 to ₹146,000.
| Key Takeaway: Gold’s recovery was built on rate relief that the jobs report took away on Friday, and it has yet to show it can hold up without it. Jewellers who stocked up for Dhanteras near ₹142,000 bought in the middle of a ₹138,000 to ₹146,000 range. A close above ₹145,968 would make that look like good timing; a close below ₹138,000 would set the decline in motion again. |
Silver | MCX SILVER1!
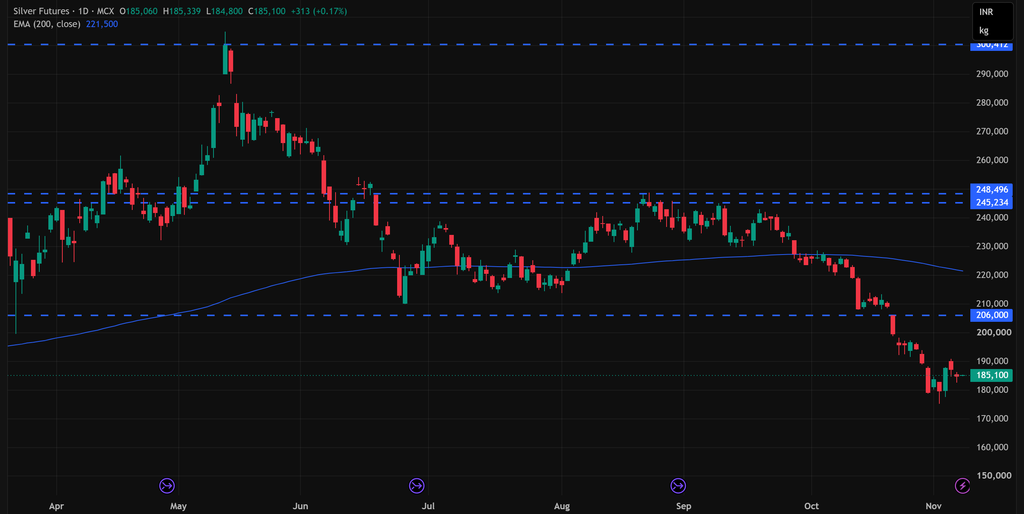
Silver fell further before it bounced. On Tuesday the December contract dipped to a new low around ₹175,000 to ₹176,000 but closed well off it, and Wednesday’s rally won back almost all of the 30 October breakdown candle, lifting price to about ₹187,500.
Thursday’s push reached roughly ₹191,000 and ran out of steam just below ₹192,149, the 23 October low and the bottom of the ₹192,000 to ₹198,000 range that held for three sessions before the late-October drop. The contract closed lower that day and drifted down again on Friday to ₹184,787. The old support level turned straight into resistance, and the pattern of lower highs and lower lows is still in place.
Silver is also much further below its trend than gold. Friday’s close is about 17% under the falling 200-day EMA at ₹221,500 (unadjusted), compared with roughly 2% for gold. Silver gained more than gold in percentage terms, yet its chart did not improve: it made a lower low, failed to make a higher high and stalled at the first resistance it met. A daily close above ₹192,000 would turn the late-October drop into a failed breakdown, while a close below ₹175,000 would extend the downtrend.
| Key Takeaway: Silver bounced from a new low and stalled at the first resistance it met, so the downtrend is still in charge. For bullion dealers and silverware makers, ₹175,000 and ₹192,000 are the levels to watch, and buying stock before a close above ₹192,000 means betting on a floor the market has not yet confirmed. |
Watch in the Days Ahead:
- US CPI, Tuesday 10 November: The first inflation data since the jobs report put hike odds back up. A hot number would show whether gold can hold its gains without rate relief, while a soft one would give the trendline break some backing from the macro side.
- Iran talks and Hormuz: Oil’s drop assumes a deal that a senior Iranian official told Reuters during the week is still far off. If talks stall or tanker attacks resume, the war premium in oil could return, and with it the inflation case against gold.
- Fed, 9 December: With a hike priced at around 75%, any Fed official who pushes back on those odds matters more for bullion than politics.
- MCX Gold: A daily close above ₹145,968 would turn the October breakdown into a failed one, and a close below ₹138,000 would restart the decline.
- MCX Silver: A close above ₹192,000 would be the first sign of a floor, and a break below ₹175,000 would extend the run of lower lows.
Disclaimer: This column is for information only and does not constitute investment advice. Prices are Friday closes for the week ending 6 November 2026; MCX figures are December contracts and exclude the 8 November Muhurat session shown as the final candle on each chart. The rupee row uses FBIL reference rates. Readers should consult a qualified adviser before making trading or inventory decisions.
Authored by Dhawal Chotai